

Analysis summary
Will specialty reinsurance rates rise at the 1 January renewal? For most of the market, probably not: abundant capacity is expected to offset heavy claims activity, with marine retrocession the one segment where rate rises are expected across the board. This analysis shows how the deterioration of the Baltimore Bridge reinsurance claim to $2.8bn is set to hit marine retro, why losses from the Iran conflict will fall more heavily on the direct market than they did after Ukraine, and why efforts to introduce conflict exclusions have so far failed. It delivers fast insight on Howden Re's estimate of a 30% rise in specialty capacity since January 2023, the estimated $2bn-$3bn of PVT losses against an estimated $1.5bn of global premium, and why the narrow group of marine retro leaders limits the competition that would otherwise hold prices down.Subscribe to get comprehensive access to our exclusive analysis in the full platform.
The marine retro market is the one segment where rate rises appear to be inevitable.
Specialty reinsurance renewals will represent a contest between the opposing forces of substantial claims activity on the one hand and growing capacity on the other – and at present, there are contrasting opinions as to which influence will prevail.
The market embarks on the renewal period facing up to the largest marine reinsurance loss ever, as well as a sprawling live conflict in the Middle East that has already resulted in billions of dollars of war claims.
On top of that, there has been substantial loss activity in the upstream and downstream energy markets, not to mention renewables, and the aviation sector continues to labour under elevated claims activity.
Despite this flurry of losses, the specialty reinsurance market is awash with capacity, and reinsurers remain hungry for business, which sources canvassed by this publication expect to mitigate any potential hardening.
Howden Re said in a mid-year report that capacity in the specialty segment is up 30% since the strained renewal of January 2023, and the market is prepared to absorb the substantial geopolitical uncertainty when renewing.
A broad consensus at this early stage in the renewal process is that the market looks likely to be largely stable, although ultimate terms could vary considerably on a case-by-case basis, depending on individual account performance.
The one pinch point where rate rises are expected across the board is the marine retrocession market, which has been pummelled by the deterioration of the Baltimore Bridge claim and settlement costs from Ukraine aircraft-leasing claims.
Sources speculated rate rises here could fall in the low double digits.
As to whether the specialty reinsurance market on a whole is priced adequately, responses vary widely between reinsurers, reflecting the spikiness and volatility of the claims activity during a period of major turbulence.
Ultimately, even this scale of specialty losses is insufficient to result in major capital erosion for global reinsurers, and eagerness to participate in the sector as a diversifier to the broader P&C market appears undimmed.
Writing through a live conflict
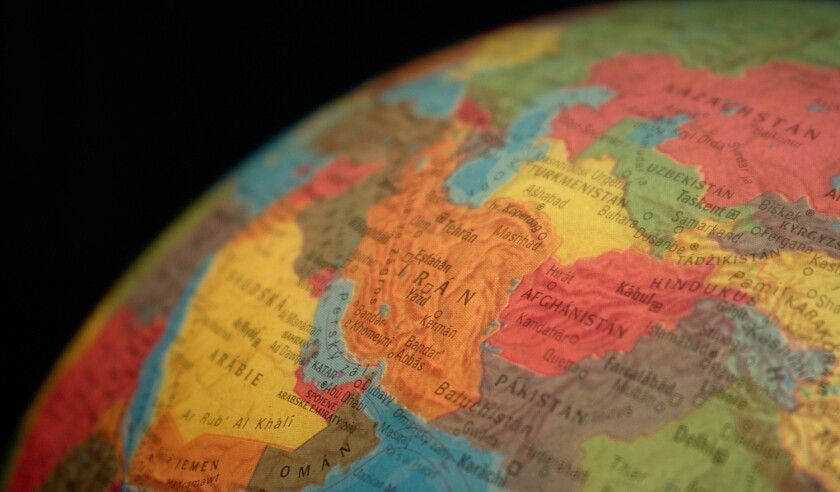
It is now more than six months since US President Donald Trump launched his war against Iran, sparking an upsurge in violence across the Middle East and bringing some of the world’s most crucial maritime trade routes to a virtual standstill.
While the situation could change at any moment, it looks a realistic possibility that the specialty market will transact upcoming 1 January renewals through a live conflict, which presents material exposure to the sector.
This was also the case at 1 April, but efforts by some carriers to impose specific conflict exclusions eventually foundered due to market competition, resulting in some turnover of panels.
While similar negotiations may yet be revived for 1 January, the same competitive pressures that prevented conflict exclusions being introduced are still present.
Iranian retaliatory bombing against Middle Eastern neighbours – mostly in the early days of the conflict – is already expected to have inflicted losses of an estimated $2bn-$3bn on the PVT market to date.
This is well above an estimated global premium income in the class estimated at approximately $1.5bn.
Because the market moved at 1 January 2023 to limit how insurers can aggregate war losses, with time-period or radius limits now being commonplace, the direct market will shoulder far more of the ultimate losses from the Iran conflict compared with Ukraine.
However, the war will still result in losses for the specialty reinsurance market, especially from major risk losses such as the $800mn Sabic claim.
Meanwhile, cumulative claims from the ongoing maritime violence in the Strait of Hormuz are expected to have resulted in insured losses at least in the high hundreds of millions.
Recent data from Skytek indicates the combined value of vessels stranded in the Gulf is more than $5bn, although most blocking and trapping exposure activates only after 12 months – and even then, insurers are adamant ships in the Gulf are not trapped, from a war-wordings perspective.
Remaining in control of aggregations will be key for reinsurers.
Reinsurers will aim to defend this position, although it is an area where brokers are likely to push for broader coverage where they can.
The market moved to largely dismantle fully composite specialty treaties in the wake of the Ukraine war, and whilst there has been some subsequent drift, there is still a focus on ensuring all exposures are priced individually.
Baltimore Bridge deterioration burns retro
The deterioration of the reinsurance claim for the 2024 Baltimore Bridge collapse to $2.8bn will have an uneven impact on cedants, depending on prior reserving decisions.
Reinsurance renewals at January 2025 and 2026 were broadly conducted on the theoretical assumption of a $1.5bn claim, although ultimate reserving decisions varied among carriers.
Some insurers with outsized exposure in the upper layers of the International Group reinsurance contract are likely to experience ugly prior-year deterioration, which reinsurers are likely to account for with rate rises.
Meanwhile, the rising cost of the claim will activate marine retro exposure, previously largely unscathed by the event.
This is the one area of the market where there is broad consensus that widespread upwards pricing pressure is inevitable, with most business renewing in Q1 or early Q2.
The marine and energy retro market is dominated by a narrow number of leaders – including Liberty Mutual Re, Axa XL Re, RenaissanceRe, Arch and Ascot – reducing the potential for competitive tensions to prevent price rises.
However, some newer entrants may eye this as an opportunity to attempt to build market share in retro through competitive pricing.
Got a tip for us? Reach out confidentially here.
Frequently asked questions
Will specialty reinsurance rates rise at the 1 January renewal?
A broad consensus at this early stage in the renewal process is that the market looks likely to be largely stable, although ultimate terms could vary considerably on a case-by-case basis, depending on individual account performance.
How much has specialty reinsurance capacity grown?
Howden Re said in a mid-year report that capacity in the specialty segment is up 30% since the strained renewal of January 2023, and the market is prepared to absorb the substantial geopolitical uncertainty when renewing.
Which part of the specialty market is expected to see rate rises?
The one pinch point where rate rises are expected across the board is the marine retrocession market, which has been pummelled by the deterioration of the Baltimore Bridge claim and settlement costs from Ukraine aircraft-leasing claims. Sources speculated rate rises here could fall in the low double digits.
What are the estimated PVT losses from the Iran conflict?
Iranian retaliatory bombing against Middle Eastern neighbours – mostly in the early days of the conflict – is already expected to have inflicted losses of an estimated $2bn-$3bn on the PVT market to date. This is well above an estimated global premium income in the class estimated at approximately $1.5bn.
Why will the direct market bear more of the Iran conflict losses than after Ukraine?
Because the market moved at 1 January 2023 to limit how insurers can aggregate war losses, with time-period or radius limits now being commonplace, the direct market will shoulder far more of the ultimate losses from the Iran conflict compared with Ukraine.
How large is the Baltimore Bridge reinsurance claim?
The deterioration of the reinsurance claim for the 2024 Baltimore Bridge collapse to $2.8bn will have an uneven impact on cedants, depending on prior reserving decisions.
Who leads the marine and energy retro market?
The marine and energy retro market is dominated by a narrow number of leaders – including Liberty Mutual Re, Axa XL Re, RenaissanceRe, Arch and Ascot – reducing the potential for competitive tensions to prevent price rises.
By Samuel Casey
8 September, 2026
Request your free trial today to unlock our complete intelligence platform. 
More from the blog
View All Posts
Market hardening is more than a reaction to headline-grabbing cat losses
Read More
SpainSat loss jolts space insurance market after brief return to profit
Read More